How Korean ISA and Tax-Advantaged Savings Accounts Work for Foreign Residents
If you've heard Korean colleagues mention an ISA account as a tax-efficient way to save and invest, and wondered whether this specific product is accessible to foreign residents, Korea's Individual Savings Account system offers genuine tax advantages for eligible savers, but understanding the specific eligibility criteria and account structure matters before assuming it works identically to a similarly-named product you might be familiar with from elsewhere.
Here's how Korea's ISA system works, and what foreign residents need to know about eligibility and structure.
What ISA Actually Is
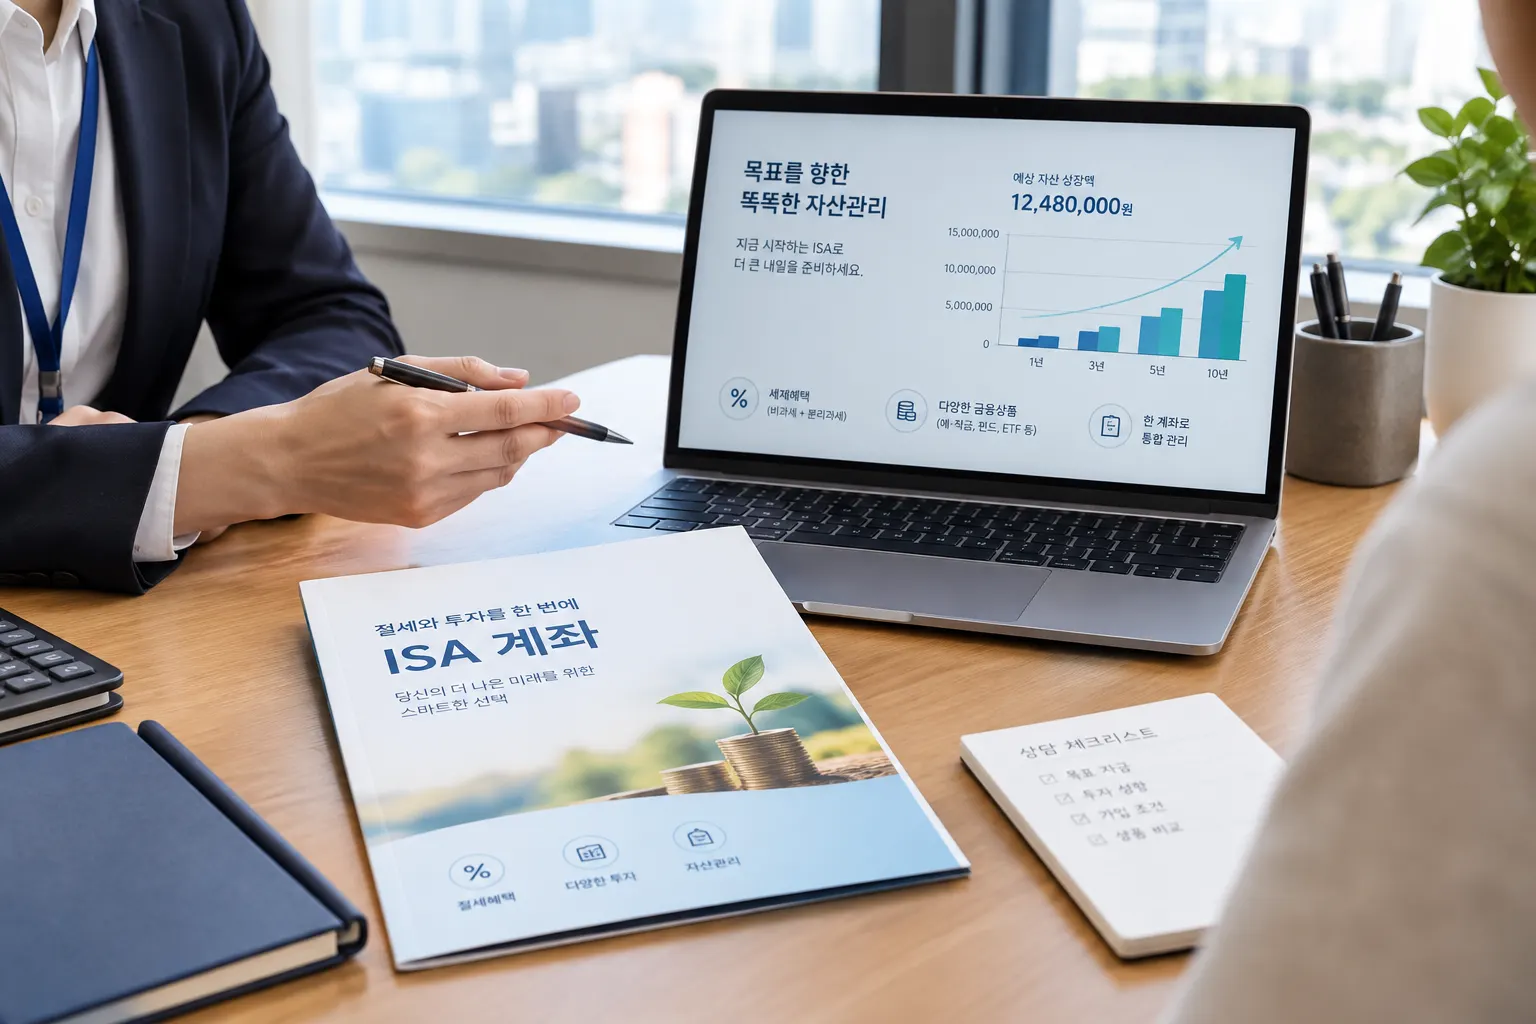
Korea's ISA (Individual Savings Account, 개인종합자산관리계좌) is a tax-advantaged account structure allowing individuals to hold various financial products, savings deposits, funds, and certain securities, within a single account offering favorable tax treatment on investment gains up to certain limits, distinct from a standard taxable brokerage or savings account.
- Tax benefits generally apply to gains within specified limits, income and gains up to a certain threshold within the account receive favorable tax treatment, exceeding this threshold, gains are still taxed but sometimes at a preferential rate compared to standard investment income taxation outside the ISA structure.
- The account generally requires a minimum holding period to realize the full tax benefit, withdrawing or closing the account before this period, generally a few years, can result in losing some or all of the intended tax advantage, understanding this commitment period matters before opening an account with funds you might need access to sooner.
- Multiple underlying product types can be held within a single ISA, savings deposits, various fund products, and certain securities, offering some flexibility in how you actually structure your holdings within the tax-advantaged wrapper.
Foreign Resident Eligibility
- ISA eligibility generally requires Korean tax residency status, rather than simply holding a standard bank account or ARC, understanding whether you meet Korea's specific tax residency criteria, generally based on the length and nature of your stay, matters for determining actual eligibility before assuming any foreign resident can open one.
- Income level and existing account restrictions sometimes apply, certain ISA account types have specific income eligibility thresholds or restrictions on holding multiple such accounts simultaneously, worth understanding the specific type of ISA product and its eligibility criteria directly with a bank or brokerage rather than assuming a single universal ISA structure applies to everyone equally.
- This is a genuinely underutilized benefit among foreign residents, many eligible foreign taxpayers in Korea simply aren't aware this option exists or assume, incorrectly, that it's restricted to Korean citizens specifically, worth investigating directly if you're a Korean tax resident interested in tax-efficient saving or investing.
How to Open and Use an ISA Account
- Confirm your Korean tax residency status, generally through a tax professional or directly with the National Tax Service if your specific situation, visa duration, income sources, isn't clearly established as tax-resident, since this underlying eligibility determines ISA access before considering the account structure itself.
- Compare ISA products across a few banks or brokerages, since specific terms, available underlying investment options, and fee structures can vary between institutions offering this account type.
- Understand the specific holding period and withdrawal rules for your chosen ISA product, since early withdrawal can affect the tax benefit you were expecting to receive, planning your contribution amount and timeline around funds you genuinely don't need immediate access to matters for actually realizing the intended tax advantage.
- Coordinate with your overall tax situation, particularly if you have complex cross-border tax obligations, an ISA's Korean tax benefit doesn't necessarily simplify or resolve separate home-country reporting requirements you may have, worth discussing with a cross-border tax professional if your overall financial situation is complex.
Common Misunderstandings
A frequent assumption among foreign residents is that Korean tax-advantaged savings products are either entirely inaccessible to non-citizens or function identically to a similarly-named product from their home country. In practice, Korean tax residency, not citizenship, generally determines eligibility, and the specific structure, tax benefit calculation, and holding period requirements are genuinely Korea-specific, worth understanding on their own terms rather than assuming direct equivalence to a familiar home-country product.
Quick Summary
- Korea's ISA system offers tax-advantaged treatment for savings and investment gains held within the account structure, up to certain limits, and generally requires a minimum holding period to realize the full benefit.
- Eligibility generally depends on Korean tax residency status rather than citizenship, many eligible foreign residents simply aren't aware this option exists or assume incorrectly that it's restricted to Korean citizens.
- Comparing specific ISA products across banks or brokerages and understanding the specific holding period and withdrawal rules matters before committing funds you might need access to sooner than the required holding period.
- Coordinating Korean ISA tax benefits with any separate home-country tax reporting obligations matters for foreign residents with more complex cross-border financial situations.